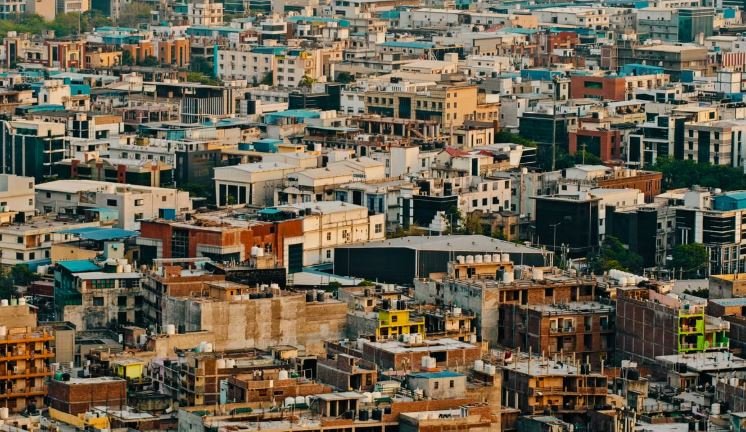
India’s affordable housing sector is creating significant opportunities for real estate developers, financial institutions and technology companies. With millions of families aspiring to own homes, demand for reasonably priced residential properties continues to influence the country’s real estate landscape. However, the challenge is no longer limited to building more houses. Making homes financially accessible, simplifying property transactions and improving construction efficiency have become equally important for the industry’s growth.
This changing market is encouraging businesses to rethink traditional approaches to property development and home financing. Digital property platforms, automated lending systems and modern construction technologies are helping companies improve operations, reach new customers and reduce unnecessary costs.
For the real estate industry, this transition represents a business opportunity that extends beyond property sales. It is creating demand for digital services, housing finance solutions, construction technology and integrated property management platforms.
Affordable Housing Is Creating a New Market for Businesses
India’s affordable housing market has considerable growth potential, with estimates indicating a requirement for approximately 22 million to 30 million affordable homes by 2030. Urban expansion, migration towards employment centres and the increasing number of first-time homebuyers are supporting this demand.
For developers, the opportunity lies in creating residential projects that meet household budgets without compromising basic construction quality, functionality and accessibility. Buyers are increasingly looking for homes that offer convenient locations, essential facilities and manageable long-term financial commitments.
However, developing affordable residential projects requires careful cost management. Land acquisition, construction materials, labour, financing expenses and regulatory procedures can significantly affect project profitability.
Developers therefore need to adopt more efficient planning and construction methods. Better project design, standardised building components and improved resource management can help control expenses while maintaining reasonable profit margins.
Government initiatives such as the Pradhan Mantri Awas Yojana (PMAY) also support the broader affordable housing ecosystem by improving access to housing assistance for eligible households. This creates opportunities for developers and housing finance providers to serve customers across different income groups.
Digital Property Platforms Are Changing the Real Estate Business
Property discovery has traditionally depended on brokers, newspaper advertisements and repeated visits to construction sites. These methods can consume considerable time and make it difficult for buyers to compare properties across different locations.
Digital property platforms are changing this process by bringing property listings, photographs, pricing information and project details together. Buyers can explore available homes, compare locations and contact developers through online channels.
For real estate companies, these platforms offer more than advertising opportunities. They provide a direct channel to reach potential customers, understand buying preferences and generate qualified enquiries.
Developers can also use customer search patterns and enquiry data to identify locations where demand is stronger. This information can support decisions about project pricing, apartment configurations and future development plans.
Virtual property tours and online consultations are particularly useful for customers who live in another city or cannot regularly visit construction sites. They can shortlist properties remotely before arranging physical inspections.
The growing adoption of digital property services is also creating opportunities for businesses offering property verification, valuation support, customer relationship management and online transaction assistance.
Digital Housing Finance Can Expand the Customer Base
Access to finance remains one of the biggest obstacles for affordable homebuyers. Many potential customers work as small traders, self-employed professionals, daily-wage earners or owners of small businesses. Although they may have regular income, they do not always maintain conventional salary slips or formal financial records.
This creates difficulties for lenders that rely heavily on traditional income verification and credit assessment methods.
Digital lending solutions can help housing finance companies and non-banking financial companies (NBFCs) improve how they evaluate loan applications. With appropriate customer consent, lenders can examine bank transactions, digital payment histories, business cash flows and other available financial information to understand a borrower’s repayment capacity.
Artificial intelligence and data analytics can further support credit assessment by identifying financial patterns and helping lenders evaluate applications more consistently.
For housing finance businesses, this creates an opportunity to reach customer segments that have historically received limited attention from traditional lending institutions.
However, technology must support responsible lending rather than encourage indiscriminate loan approvals. Human oversight, data privacy, transparent loan terms and proper risk assessment remain essential.
Automation Can Improve Efficiency for Housing Finance Companies
The housing loan process involves several activities, including application collection, identity verification, income assessment, property valuation and documentation. When these processes depend heavily on manual work, they can increase administrative expenses and delay customer decisions.
Automation can help financial institutions manage these activities more efficiently.
Digital systems can organise applications, identify missing documents, support verification procedures and track loan progress. Automated workflows can also reduce repetitive administrative tasks and help employees focus on customer service and complex credit decisions.
For NBFCs and housing finance companies, these improvements can support business expansion without requiring operational resources to increase at the same pace as loan volumes.
Faster processing can also improve customer satisfaction. Homebuyers often coordinate property bookings, down payments and loan approvals within limited timeframes. Delays can create uncertainty and sometimes result in lost sales opportunities for developers.
This makes technology an important investment for lenders seeking to improve both operational performance and customer relationships.
Modern Construction Methods Can Protect Developer Margins
Affordable housing requires a different approach to project planning. Simply reducing apartment sizes or removing amenities does not necessarily make a project commercially sustainable.
Developers must examine how construction costs can be controlled from the initial design stage.
Modular design and precast construction offer potential advantages in this area. Instead of producing every structural component through conventional on-site processes, precast technology allows elements such as walls, beams, columns and slabs to be manufactured using reusable moulds and assembled at the project location.
Standardised designs can improve material planning, reduce wastage and make construction schedules more predictable. Reusable steel moulds can also support repeated production of similar components across large residential projects.
Another advantage is improved coordination between architects, engineers, contractors and material suppliers. When project requirements are planned in advance, businesses can reduce unnecessary changes and improve the use of labour and equipment.
For developers, the commercial benefit comes from better cost control, more efficient resource utilisation and the potential to complete projects within shorter timelines.
Construction technology companies can also benefit from this shift by providing prefabricated components, modular design services, project monitoring systems and specialised construction equipment.
New Opportunities for Proptech and Fintech Businesses
The development of affordable housing is creating a wider business ecosystem in which technology companies can provide services at different stages of the property purchase journey.
Some of the most promising business opportunities include:
Digital property marketplaces: Businesses can build platforms that connect developers, brokers and homebuyers. Revenue opportunities include property advertising, lead generation and developer partnerships.
Housing finance technology: Fintech companies can develop digital solutions for loan applications, customer onboarding, document management and credit assessment in partnership with regulated financial institutions.
Property valuation and verification: Technology providers can help lenders and buyers access property information, support valuation processes and organise ownership-related documentation.
Construction management solutions: Businesses can offer software for project planning, material tracking, contractor coordination and cost monitoring.
Customer support services: Digital service providers can assist buyers with property comparisons, loan documentation, transaction coordination and post-purchase requirements.
These opportunities are particularly relevant in Tier-2 and Tier-3 cities, where growing housing demand is creating a need for better property information, organised financing services and professional real estate support.
Why Transparency Will Become a Competitive Advantage
Buying a home involves a substantial financial commitment. Customers need confidence in the developer, property documents, construction quality and final purchase price before making a decision.
Digital platforms can help improve transparency by presenting property details, project approvals, pricing information and construction updates in an organised manner.
For developers, providing accurate information can improve customer confidence and strengthen their market reputation. For financial institutions, clear communication about eligibility, interest rates, repayment schedules and additional charges can reduce confusion during the lending process.
Property platforms also need to ensure that listings and project information are properly verified. A convenient digital interface has limited value if buyers cannot rely on the information being presented.
Businesses that prioritise transparency and customer service can build stronger relationships and generate repeat business through referrals.
The Growing Role of Smaller Cities
Affordable housing opportunities are not limited to India’s largest metropolitan markets. Smaller cities are becoming increasingly important as employment opportunities, infrastructure development and urban expansion influence residential demand.
For developers, these locations may offer opportunities to design projects around local income levels, household requirements and land availability.
However, entering smaller markets requires an understanding of local purchasing capacity, employment patterns and property regulations. A housing model that works in a metropolitan city may not necessarily be suitable for a smaller urban centre.
Digital platforms can help businesses understand local demand and connect with buyers who may otherwise have limited access to organised property services.
Housing finance companies can also use technology to expand their presence across regions while maintaining consistent documentation and assessment processes.
Challenges Businesses Need to Address
Despite the opportunities, affordable housing businesses must manage several operational and financial challenges.
Land costs, construction expenses, regulatory approvals and project financing can affect the commercial viability of residential developments. Lenders must carefully assess repayment capacity, property valuations and regional risks before extending loans.
Digital platforms also need reliable property information, secure customer data systems and strong verification processes. Technology cannot completely replace legal checks, physical property inspections or responsible financial assessment.
For developers and financial institutions, the most effective approach will be to combine digital efficiency with local market knowledge and professional oversight.
The Business Outlook for India’s Affordable Housing Sector
India’s affordable housing market is evolving into a broader business opportunity involving real estate development, financial services, digital platforms and construction technology.
For developers, the priority will be to build homes more efficiently while maintaining quality and financial sustainability. For lenders, digital assessment and automated operations can help expand access to housing finance and improve business efficiency. For technology companies, the market offers opportunities to develop solutions that simplify property discovery, financing, verification and construction management.
The future growth of the sector will depend on how effectively businesses address the everyday challenges faced by homebuyers. Lower construction costs, accessible financing, reliable property information and faster transactions can make a meaningful difference to the overall housing experience.
Ultimately, affordable housing is not just a real estate opportunity. It is a growing business ecosystem where technology, finance and construction need to work together. Companies that understand this connection and build practical, customer-focused solutions will be better positioned to benefit from India’s expanding demand for affordable homes.