Pic Credit: Pexel
Global supply chains have become a critical factor in business competitiveness, influencing everything from production costs and delivery schedules to customer satisfaction and profitability. For Indian businesses, geopolitical tensions, shipping disruptions, rising freight charges and dependence on imported materials have made supply chain management increasingly complex. A delay at an overseas port or a shortage of a key component can affect factory output, disrupt export commitments and place pressure on working capital.
This changing environment is prompting companies to rethink a long-standing business priority: keeping inventory and operating costs as low as possible. Efficiency remains important, but it is no longer enough on its own. Businesses must also be prepared to respond when suppliers fail, transport routes become unreliable or international trade conditions change unexpectedly.
The shift is particularly significant for India’s manufacturing, automotive, textiles, electronics, retail and export sectors. For MSMEs, which often operate with tighter margins and limited financial reserves, a supply disruption can quickly move beyond an operational inconvenience to become a serious business challenge.
When Global Disruptions Reach Indian Markets
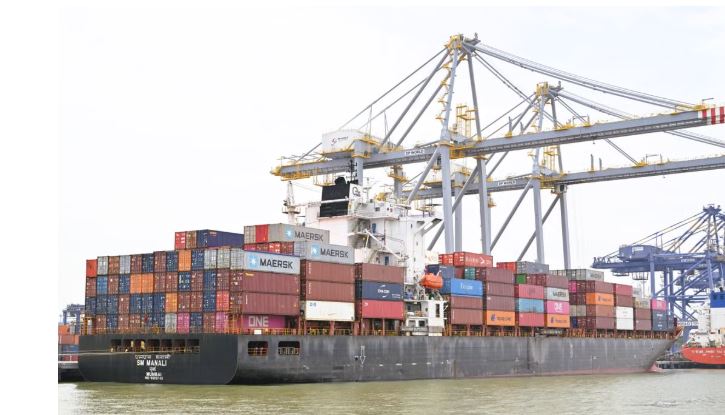
International supply chains are interconnected, meaning that a disruption in one region can have consequences far beyond its immediate location. Conflicts affecting important maritime routes, congestion at shipping hubs and changes in insurance premiums can increase the time and cost required to move goods.
The West Asia crisis has highlighted these vulnerabilities for Indian exporters and importers. Shipping diversions and additional war-risk costs can make deliveries more expensive and less predictable, particularly for businesses serving markets in the Gulf and other international destinations.
The impact extends beyond companies that directly import or export goods. A domestic manufacturer may depend on imported machinery or electronic components, while a retailer may rely on packaging materials whose prices are influenced by international markets. When these costs rise, businesses must decide whether to absorb the increase, renegotiate contracts or pass part of it on to customers.
For exporters, the challenge is equally complex. Delayed shipments can affect delivery commitments, disrupt payment schedules and weaken relationships with international buyers. Smaller firms may be particularly exposed because they have fewer alternative routes, suppliers or financing options available at short notice.
Sector-by-Sector: Where the Pressure Is Greatest
Manufacturing and automotive: Keeping production on schedule
Manufacturers need reliable access to raw materials, spare parts, chemicals and specialised components. If a critical input fails to arrive, even a well-equipped factory may be unable to complete production.
Automotive and electronics manufacturers face particular challenges because their products often depend on components sourced from multiple countries. A shortage in one part of the supply chain can delay an entire production line, increase inventory costs and affect deliveries to dealers or customers.
Businesses can reduce this exposure by identifying components that have long replacement lead times, qualifying alternative suppliers and developing contingency plans for essential materials.
Exporters and logistics: Protecting delivery commitments
For exporters, freight rates are only one part of the challenge. Longer transit times, cargo insurance costs, port congestion and uncertainty over delivery dates can affect the economics of an order.
An export contract negotiated at a particular price may become less profitable if transport expenses rise before the shipment leaves the country. Delays can also tie up money in goods that have been dispatched but not yet delivered or paid for.
Exporters therefore need to evaluate the full cost of fulfilling an order, maintain regular communication with buyers and logistics partners, and assess whether contract terms adequately account for changes in transport costs and delivery schedules.
Retail and consumer goods: Balancing availability and affordability
Retailers and distributors depend on predictable replenishment to keep products available without tying up excessive capital in stock. Disruptions can leave popular items unavailable while increasing the cost of replacement inventory.
Businesses may be forced to choose between holding additional stock and risking lost sales. If procurement and transportation costs continue to rise, some of the increase may eventually reach consumers.
Better demand forecasting, closer coordination with suppliers and careful monitoring of fast-moving products can help retailers balance availability with affordability.
MSMEs and traditional industries: Managing limited financial flexibility
Smaller manufacturers, artisans and export-oriented businesses can be especially vulnerable to sudden changes in logistics costs. They may lack the purchasing power to negotiate favourable freight rates or the financial capacity to hold large quantities of reserve inventory.
For such businesses, delayed payments and rising input costs can create a working-capital squeeze. Money needed to pay employees, purchase materials or fulfil new orders may remain tied up in delayed consignments.
Their response does not necessarily require expensive technology. Better order tracking, regular supplier reviews, realistic delivery commitments and a modest reserve of essential materials can make a meaningful difference.
From Just-in-Time to Just-in-Case: Finding the Right Balance
For decades, just-in-time inventory management helped companies reduce storage costs by receiving materials close to when they were required. Under stable conditions, this approach can improve efficiency and limit the amount of capital tied up in stock.
However, lean inventory can become a weakness when supplies are interrupted. Many businesses are therefore adopting a more balanced approach, combining efficient purchasing with carefully selected safety stocks and backup suppliers.
The goal is not to accumulate inventory indiscriminately. Excess stock increases warehousing expenses, creates the risk of obsolescence and reduces the cash available for other business needs.
A more effective strategy begins with identifying materials that could stop production or significantly affect sales if unavailable. Businesses can then determine appropriate safety-stock levels based on supplier reliability, delivery lead times, demand patterns and the financial consequences of a shortage.
This approach allows companies to protect essential operations without sacrificing the cost discipline required for sustainable growth.
Six Practical Steps to Build a More Resilient Supply Chain
1. Reduce dependence on a single supplier
Businesses should assess whether critical materials can be sourced from more than one qualified supplier. Diversification may involve domestic vendors, alternative international markets or different transport routes. Before switching, companies should verify quality, capacity, pricing and delivery reliability.
2. Map the supply chain beyond direct suppliers
A business may know its immediate vendor but have limited visibility into where that vendor obtains its own materials. Mapping critical suppliers and their dependencies can reveal hidden risks before they disrupt production.
3. Use digital tools to anticipate problems
Inventory management systems, shipment tracking and data-driven demand forecasting can help businesses identify potential shortages earlier. Larger enterprises may benefit from AI-powered planning tools, while smaller firms can start with integrated spreadsheets or affordable cloud-based software.
Technology is most useful when information is accurate, updated regularly and linked to clear decisions about purchasing and production.
4. Protect working capital
Supply disruptions often increase the time between spending money on materials and receiving payment from customers. Businesses should regularly review cash-flow forecasts, outstanding invoices, supplier payment terms and the cost of holding inventory.
Financial planning should also account for possible increases in freight, insurance and procurement costs rather than assuming that current expenses will remain unchanged.
5. Review contracts and insurance
Importers and exporters should understand how their contracts address delivery delays, changes in shipping costs, liability and unforeseen disruptions. Cargo insurance, where appropriate, should be reviewed carefully to understand the risks covered, exclusions and claim requirements.
Professional advice may be necessary before agreeing to unfamiliar clauses or complex foreign trade arrangements.
6. Explore domestic sourcing and government support
Domestic suppliers can offer shorter lead times and reduce exposure to some international transport risks. Government initiatives, including Production-Linked Incentive schemes in eligible sectors, aim to strengthen manufacturing capacity in India.
However, local sourcing should be evaluated on total cost, product quality, production capacity and reliability. A resilient supply chain is built on suitable alternatives, not simply on replacing one source with another.
The Business Case for Resilience
Supply chain resilience is increasingly linked to a company’s ability to protect profits, retain customers and deliver consistent service. It can also influence investment decisions: businesses with reliable procurement and contingency plans may be better positioned to scale production and enter new markets.
For Indian companies, the opportunity lies in combining operational efficiency with better preparation. Diversified sourcing, selective inventory buffers, digital visibility and disciplined cash-flow management can help reduce exposure to unexpected shocks.
No business can eliminate every external risk. However, companies that understand their vulnerabilities and prepare practical responses can limit disruption and recover more quickly when conditions change.
In a volatile global economy, competitive advantage will depend not only on how cheaply a business can produce or deliver a product, but also on how reliably it can do so when the unexpected happens.