A growing business does not always have enough cash to keep its operations running smoothly. Even when orders are increasing and customers are showing interest, delayed payments, rising expenses and excess inventory can put pressure on available funds. For many Indian businesses, particularly small enterprises and MSMEs, managing this gap between money coming in and money going out is one of the biggest challenges to sustainable growth.
Working capital is the money a business needs to manage its everyday activities. From purchasing raw materials and maintaining inventory to paying employees and settling supplier bills, almost every business operation depends on the timely availability of funds.
In a competitive business environment, generating revenue is only one part of financial success. Companies also need to ensure that their money is managed efficiently. Poor cash flow planning can delay expansion, affect supplier relationships and make it difficult to fulfil new orders.
For Indian MSMEs, which often operate with limited financial resources, a disciplined approach to working capital can make a meaningful difference. Here are eight practical strategies that can help businesses manage cash flow, reduce financial pressure and prepare for long-term growth.
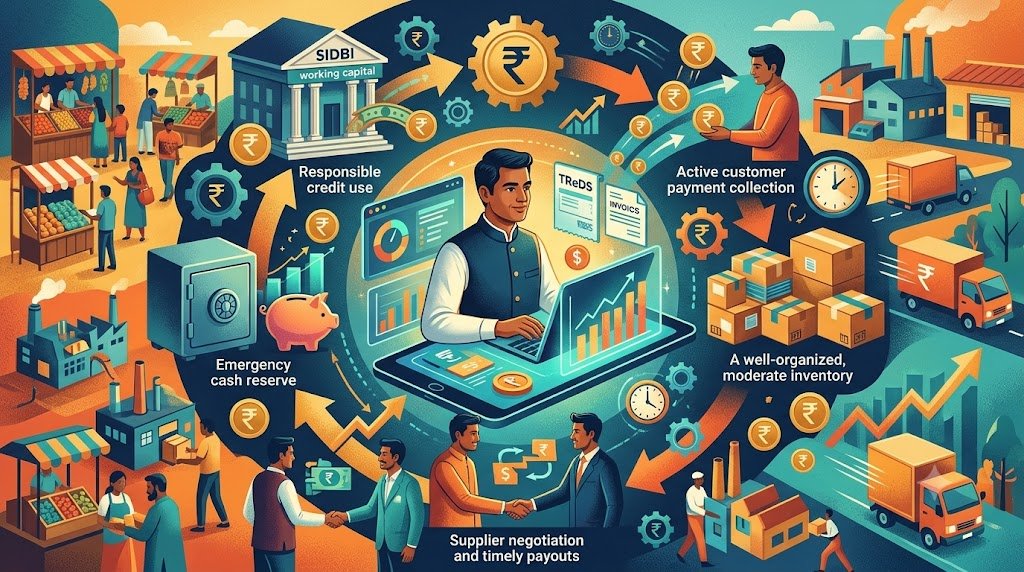
1. Improve Customer Payment Collection
One of the most common reasons businesses experience cash shortages is delayed customer payments. A company may complete an order or deliver a service on time, but if the customer takes several weeks or months to pay, the business may struggle to meet its own expenses.
To avoid this situation, businesses should establish clear payment terms before accepting orders. Regular invoice tracking, timely reminders and direct follow-ups can encourage customers to clear outstanding payments without unnecessary delays.
Companies should also review the payment history of customers before offering credit. Where suitable, early-payment discounts can motivate buyers to settle invoices sooner.
For MSMEs working with larger companies, consistent follow-ups and proper documentation are particularly important. Faster collections help businesses maintain liquidity and reduce their dependence on short-term borrowing.
2. Use TReDS to Unlock Money from Unpaid Invoices
For many small businesses, unpaid invoices represent money that has been earned but is not yet available for use. Waiting for buyers to complete their payment cycles can affect purchasing decisions, employee payments and the ability to accept new orders.
The Trade Receivables Discounting System (TReDS) provides an alternative way to access funds. It is an electronic platform that enables eligible MSMEs to get their approved trade receivables financed by banks and other financiers before the invoice due date.
This allows suppliers to receive money earlier instead of waiting for the buyer’s payment. The funds can then support everyday business requirements, including raw material purchases, salaries and supplier payments.
Businesses should compare financing charges and understand the terms before using invoice discounting. When used carefully, TReDS can help reduce the pressure created by long payment cycles.
3. Manage Inventory Without Blocking Too Much Money
Inventory is necessary for meeting customer demand, but holding more stock than required can tie up a significant amount of business capital. Products that remain unsold for long periods increase storage costs and may eventually lose value.
Retailers, manufacturers and distributors should regularly review their stock levels and identify products that sell quickly and those that move slowly. Understanding seasonal demand and previous sales trends can also improve purchasing decisions.
For example, businesses preparing for festive seasons may need additional inventory, but purchases should be based on realistic demand rather than assumptions. Digital inventory systems can help track stock movement, avoid unnecessary orders and identify slow-moving products.
The objective is to maintain enough inventory to serve customers while keeping funds available for other important business activities.
4. Negotiate Practical Payment Terms with Suppliers
Working capital management is not only about receiving payments faster. It also involves managing outgoing payments carefully.
Businesses that pay suppliers immediately but collect money from customers after several weeks may face unnecessary cash flow pressure. Negotiating reasonable credit periods with suppliers can help reduce this gap.
For example, if a business generally receives customer payments after 45 days, it can discuss a suitable supplier payment schedule that provides enough time to manage its finances.
However, extending payment periods should not come at the expense of supplier relationships. Clear communication, reliable ordering patterns and payments within agreed deadlines help build trust and may create opportunities for more flexible arrangements.
5. Monitor the Cash Conversion Cycle
The cash conversion cycle helps businesses understand how quickly the money invested in daily operations returns through sales. It considers how long products remain in inventory, how much time customers take to make payments and when the business needs to pay its suppliers.
A shorter cash conversion cycle generally means that money comes back into the business faster. This gives companies greater flexibility to manage operating expenses, purchase new stock and invest in growth opportunities.
Businesses should regularly review how quickly inventory is sold, how long customers take to clear invoices and whether supplier payments are being managed efficiently. Monitoring these areas every month can reveal where money is getting held up.
For example, if products are taking too long to sell or customers are regularly delaying payments, businesses can take corrective steps before the situation affects daily operations. Better monitoring also supports smarter purchasing, pricing and credit decisions.
6. Build an Emergency Cash Reserve
Unexpected expenses are part of running a business. A major customer may postpone a payment, raw material prices may increase or equipment may need urgent repairs. Without sufficient reserves, even a profitable company can find it difficult to manage such situations.
Maintaining an emergency cash reserve can provide financial support during uncertain periods. Businesses should assess their essential monthly expenses and gradually set aside funds based on their operating requirements and revenue stability.
This reserve should remain separate from regular operating money and be kept in an accessible financial option suited to the company’s needs.
Having a financial buffer can help businesses pay salaries, manage essential bills and continue operations without immediately depending on expensive emergency loans.
7. Use Working Capital Loans Responsibly
Short-term credit facilities such as Cash Credit and Overdraft can help businesses manage temporary gaps between customer collections and operating expenses.
For example, a manufacturer may receive a large order but need funds to purchase raw materials before receiving payment from the buyer. A working capital facility can help meet this immediate requirement.
However, borrowing should be linked to a genuine business need. Short-term loans are generally better suited to inventory purchases, supplier payments and other routine operating requirements rather than long-term investments.
Before taking a loan, businesses should compare interest rates, processing charges, repayment conditions and other costs. They should also avoid borrowing more than they can comfortably repay.
MSMEs can explore suitable financing options through banks and institutions such as SIDBI, depending on their eligibility and funding requirements.
8. Adopt Digital Tools for Better Cash Flow Planning
As businesses expand, managing every invoice, expense and payment manually can become difficult. When financial information is scattered across different spreadsheets and records, it becomes harder to understand the actual cash position of the company.
Digital accounting and financial management tools can make this process more organised. Businesses can use software that supports invoice tracking, expense management, bank reconciliation and GST-related accounting to maintain updated financial records.
Cash flow forecasting is equally important. By preparing estimates for the next 30, 60 or 90 days, companies can anticipate customer collections, supplier payments, salaries, taxes and other expenses.
If a business identifies a possible cash shortage in advance, it can follow up on pending invoices, adjust purchasing plans or arrange suitable financing before the problem becomes serious.
Digital tools also reduce repetitive administrative work and allow business owners to spend more time on financial planning and business development.
Why Working Capital Management Matters for Indian MSMEs
For India’s MSME sector, managing available funds is just as important as accessing finance. A business may have strong demand and a growing customer base, but poor cash flow can prevent it from purchasing materials, fulfilling orders or expanding its workforce.
Effective working capital management helps businesses maintain regular operations, reduce unnecessary borrowing and build stronger relationships with customers and suppliers. It also allows companies to prepare for seasonal changes, manage unexpected expenses and make better investment decisions.
Financial discipline can improve business confidence as well. Organised accounts, clear payment records and realistic cash flow forecasts help companies understand their financial position and prepare for future funding requirements.
Conclusion
Business growth is not just about increasing sales; it is also about managing money wisely. A company may attract new customers and receive more orders, but without timely collections, balanced inventory and proper financial planning, expansion can put additional pressure on its resources.
For Indian businesses, especially MSMEs, working capital management should be a regular part of business planning. Improving payment collection, using TReDS where suitable, negotiating supplier terms, controlling inventory and adopting digital financial tools can help companies make better use of their available funds.
Ultimately, the goal is to ensure that money moves efficiently through the business and remains available when it is needed most. With consistent financial discipline and careful planning, businesses can manage everyday challenges more confidently and build a stronger foundation for sustainable growth.