
Ireland’s growing shift towards digital payments is changing how people shop, manage their money and interact with businesses. From contactless cards at local shops to mobile wallets used for everyday purchases, digital transactions are becoming an increasingly familiar part of Irish life. The change reflects more than a preference for convenience. It is also reshaping the way retailers operate, financial services compete and consumers make spending decisions.
As cash becomes less central to routine transactions, businesses are under growing pressure to offer faster and more flexible payment options. At the same time, the transition raises important questions about transaction costs, financial security and access to essential services for people who still depend on physical money.
Ireland’s Move Away From Cash Gains Momentum
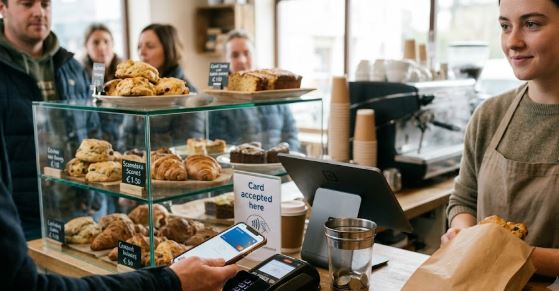
For many Irish consumers, carrying large amounts of cash is no longer necessary. Contactless cards and smartphone-based payments allow shoppers to complete everyday purchases quickly, whether they are buying groceries, paying for transport or enjoying a meal at a restaurant.
The popularity of these methods has grown alongside wider changes in consumer behaviour. People increasingly expect transactions to be straightforward, particularly when shopping in busy retail environments where long queues can affect the overall experience.
Digital payments also offer a practical advantage: consumers can review transactions through banking applications and track where their money goes. However, this convenience does not automatically translate into better financial management. Easy payments can sometimes make spending feel less tangible, potentially encouraging impulse purchases or making it harder for some households to monitor small, frequent expenses.
Cash therefore continues to serve an important purpose, particularly for people who prefer physical budgeting or want greater control over daily spending.
Mobile Wallets Change the Shopping Experience
Mobile wallets have emerged as an important driver of Ireland’s digital payment transition. Services such as Apple Pay and Google Pay allow customers to make payments using compatible smartphones and other devices, reducing the need to carry a physical wallet.
For consumers, the appeal lies in speed and simplicity. A payment can be completed within seconds, while digital authentication features can add an additional layer of protection. The integration of payments into mobile devices also reflects a broader trend towards services that combine shopping, banking and personal finance in one digital environment.
Retailers are adapting to these expectations by upgrading payment terminals and offering multiple ways to pay. In supermarkets, cafés, restaurants and smaller shops, accepting contactless payments has become an important part of delivering a convenient customer experience.
Yet businesses must ensure that technological upgrades deliver genuine value. Payment processing fees, equipment costs and software expenses can place pressure on smaller retailers, particularly those operating with limited margins. The challenge is to improve convenience without allowing the cost of accepting payments to erode profitability.
Digital Payments Create New Opportunities for Businesses
The expansion of electronic payments is creating opportunities beyond faster checkout services. Digital transaction records can help businesses reconcile accounts, monitor sales and identify patterns in customer spending. These insights can support inventory planning, financial management and decisions about staffing during busy periods.
For small and medium-sized enterprises, digital payment systems can also reduce some of the administrative work associated with handling cash. More efficient transaction records may make it easier to maintain accounts and prepare financial information.
The benefits extend to the financial services industry. Banks, payment providers and financial technology companies are competing to deliver secure, reliable and user-friendly services. This competition is encouraging innovation in mobile banking, payment authentication and the integration of financial tools.
However, digital adoption is not equally easy for every business. Smaller enterprises may need additional support to understand transaction charges, select suitable payment providers and protect their systems against fraud. For them, the transition is as much a business-cost decision as a technological one.
Security and Consumer Confidence Remain Critical
As digital transactions become more common, protecting consumers from fraud is increasingly important. Phishing messages, fraudulent payment requests, stolen account details and scams targeting mobile banking users can threaten both personal finances and confidence in electronic payment systems.
Consumers must remain cautious about unexpected messages, suspicious links and requests to disclose banking information. Businesses and payment providers also have a responsibility to strengthen security systems, identify unusual transactions and make it easier for customers to report problems.
Security is particularly important because trust influences whether consumers continue using digital services. A payment system may be fast and convenient, but repeated fraud incidents or difficulties recovering money can discourage adoption.
Clear communication, reliable customer support and effective safeguards will therefore remain essential as Ireland’s payment ecosystem develops.
Why Cash Access Still Matters
Despite the rapid expansion of digital transactions, a completely cashless economy would not necessarily benefit everyone. Some older consumers may be less comfortable with mobile technology, while people with disabilities or limited access to digital services may encounter barriers when using electronic payment systems.
Cash can also provide a practical alternative during internet outages, technical failures or other disruptions. For some households, using physical money remains an effective way to set spending limits and avoid overspending.
Ireland’s national payments policy must therefore balance innovation with inclusion. Encouraging digital adoption should not mean removing reasonable access to cash or making essential services unnecessarily difficult for people who cannot readily use digital alternatives.
Maintaining a choice of payment methods can help ensure that technological progress serves consumers across different age groups, income levels and circumstances.
The Future of Payments in Ireland
Ireland’s digital payment transformation is likely to deepen as consumers become more comfortable with mobile wallets, contactless cards and integrated financial services. Retailers will need to keep pace with these expectations while managing costs, protecting customer information and maintaining reliable payment facilities.
The wider economic impact will depend on how effectively businesses use digital systems to improve efficiency and how well consumers are protected from financial risks. Digital payments can make commerce faster and financial records easier to manage, but their benefits must be weighed against processing expenses, cybersecurity threats and the risk of excluding vulnerable groups.
Ultimately, the future of payments in Ireland will not be determined simply by how quickly cash disappears. It will depend on whether the financial system can combine convenience, affordability, security and choice.
For consumers, digital payments are becoming an everyday part of modern life. For businesses, they are increasingly important to customer service and operational efficiency. The real opportunity lies in building a payment system that supports both economic innovation and the financial needs of the people who use it.